BY: PHESHEYA KUNENE | EDITOR
MANZINI — Eswatini’s sugarcane growers may receive one of the stronger shares of sugar proceeds in the COMESA region, but the Eswatini Cane Growers Association (ECGA) says that should not be mistaken for evidence that local farmers are financially better off.
ECGA has welcomed findings of a regional sugar industry study highlighted by the Times of Eswatini, which places Eswatini among countries where growers receive a comparatively high proportion of industry proceeds.
Under Eswatini’s Division of Proceeds arrangement, growers receive 68.1 per cent of divisible proceeds, while millers receive 31.9 per cent. The regional study puts Mauritius at 78 per cent, Zimbabwe at 77 per cent, Kenya at 63 per cent, and Malawi and Zambia at 60 per cent.
On paper, Eswatini looks good. On the farm, ECGA argues, the picture is considerably more complicated.
A BIGGER SHARE DOES NOT ALWAYS MEAN A BIGGER PROFIT
The Association’s central argument is that comparing revenue shares without comparing the cost of producing a tonne of cane risks telling only half the story.
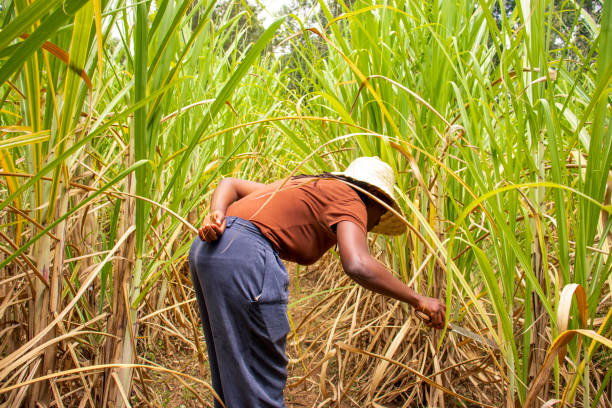
More than 90 per cent of Eswatini’s independent cane growers are small scale producers, many operating farms of between three and 50 hectares. Unlike large estates, these growers have limited room to spread machinery, labour, management and other fixed costs across thousands of hectares.
More importantly, Eswatini’s sugarcane crop is irrigated. Water has to be pumped, making electricity an unavoidable cost of production rather than an occasional expense.
That pressure increased on 1 April 2026 when the average electricity tariff rose by 11.74 per cent, following government intervention that reduced the original 13.61 per cent regulatory award.
This is where regional league tables become less useful. Sugar industries operate under different climates, irrigation systems, farm structures and cost bases. A grower receiving a smaller percentage elsewhere may not necessarily face the same electricity, pumping and production costs as an Eswatini farmer.
For ECGA, therefore, 68.1 per cent measures how divisible proceeds are allocated. It does not, by itself, measure profitability.
YIELDS TELL THE HARDER STORY
The pressure is visible in the fields.
Official Eswatini Sugar Association figures show average cane yield falling from almost 108 tonnes per hectare in 2018/19 to 88.05 tonnes in 2023/24. It recovered modestly to 89.94 tonnes in 2024/25 and 91.06 tonnes in 2025/26, but remains well below the level achieved seven years ago.
ESA’s own industry review has identified poor crop management, adverse climatic conditions, deteriorating soil health and increasing pest and disease pressure among the important factors behind weaker yields.
That matters because a farmer can receive a respectable share of industry revenue and still see margins squeezed if fewer tonnes are harvested from each hectare while electricity, transport, fertiliser, labour and certification costs rise.
Certification adds another layer. Access to increasingly sustainability conscious sugar markets requires growers to comply with standards and absorb the associated implementation, maintenance and audit costs.
THE NEXT FIGHT IS OVER THE FULL CANE STALK
The COMESA findings nevertheless strengthen one important principle: growers are not simply suppliers to the sugar industry. They are partners at the beginning of its value chain.
Before cane reaches a mill, growers have already financed land preparation, planting, irrigation, fertiliser, crop protection, labour and harvesting, while carrying much of the agricultural risk.
ECGA therefore believes the next discussion should extend beyond the headline percentage to the total value created from cane.
Sugarcane produces more than sugar. Bagasse can support cogeneration, while molasses, filter cake and other streams create additional commercial value. The regional comparison is particularly interesting because growers in Mauritius can participate in proceeds from some by products, while arrangements differ elsewhere.
ECGA’s position is that local growers should ultimately receive fair compensation for what it describes as the full stick of cane, with such discussions conducted through established industry structures and in partnership with millers.
Eswatini does have an important advantage: a comparatively organised industry operating through established legislation, institutions and revenue sharing arrangements. That framework is particularly valuable to small scale growers who would otherwise have far less bargaining power.
The COMESA study should therefore be read as neither a victory lap nor an indictment of the current system. It is a benchmark.
Eswatini’s 68.1 per cent grower share compares favourably regionally. The harder question is how much remains in the farmer’s pocket after producing the cane.
For an industry built on thousands of hectares of irrigated fields, that distinction matters. A sustainable sugar industry ultimately requires sustainable growers.